
AI Debt Is Starting to Reprice: Can Big Tech Still Afford the CapEx Boom?
Hyperscaler debt issuance is surging, bond demand is weakening, and matched AI bonds are trading 15–22bp wider. Capital may be becoming AI's next bottleneck.
Hyperscaler debt issuance is surging, bond demand is weakening, and matched AI bonds are trading 15–22bp wider. Capital may be becoming AI's next bottleneck.
Memory inventories below 10 days matter because the industry is running out of the inventory buffer that normally absorbs unexpected changes in demand. HBM4, long-term customer agreements and uncommitted bit supply now matter more than another HBM demand forecast.
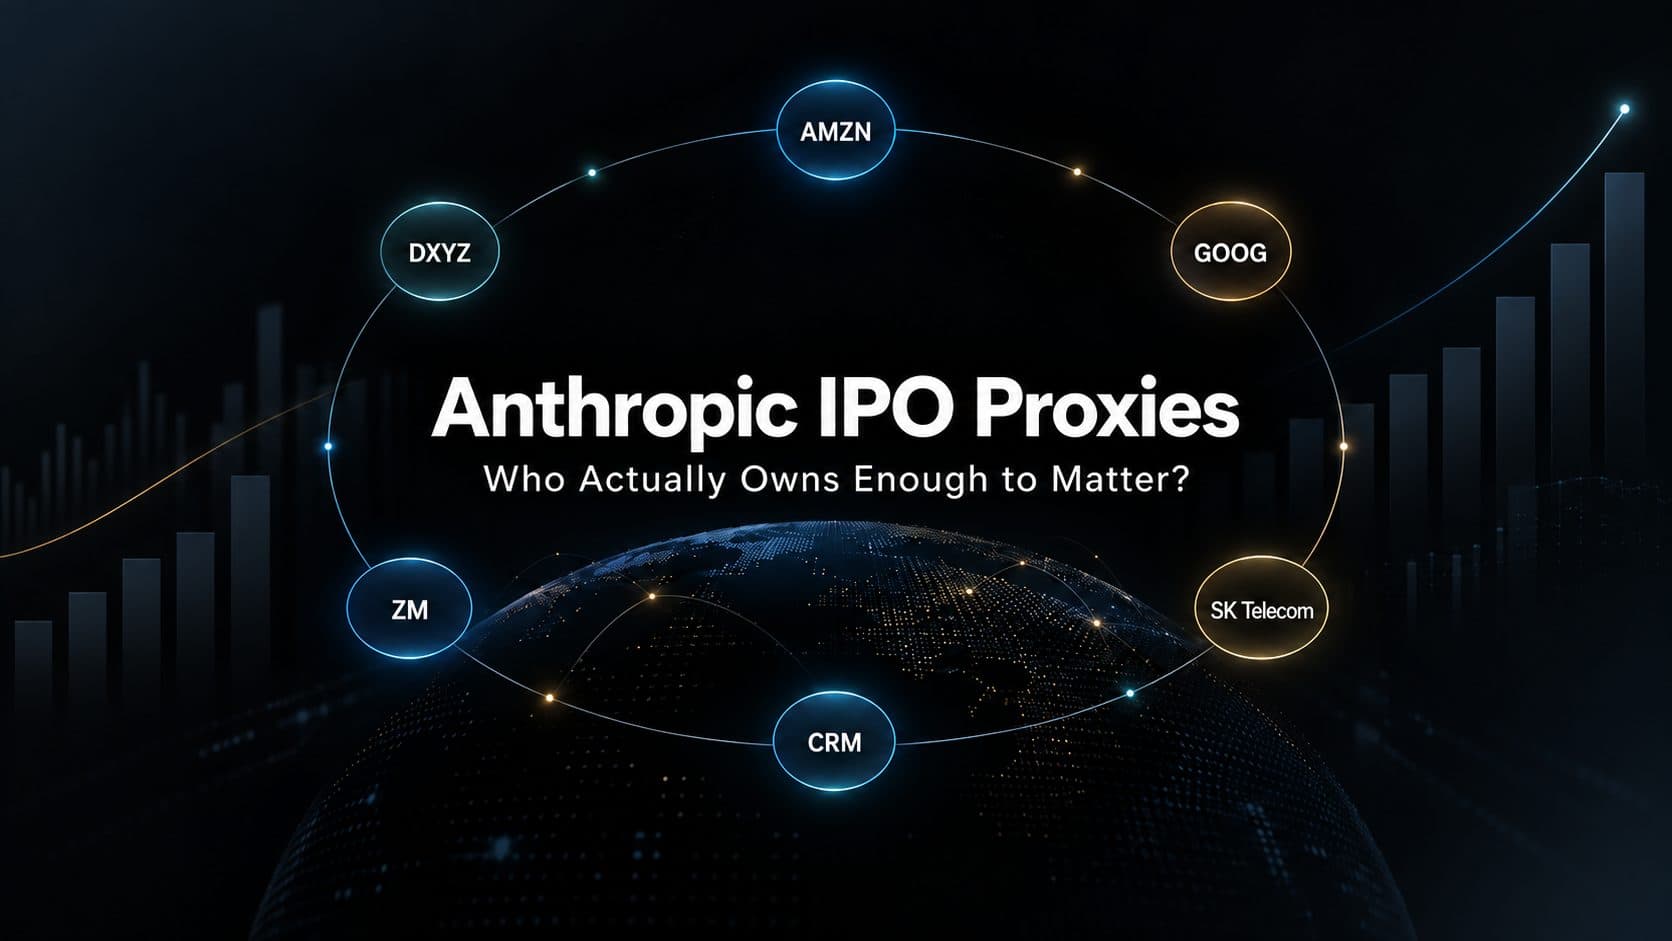
The best Anthropic IPO proxy is not the company that owns the most Anthropic. It is the public company whose market value is most concentrated in its Anthropic position — which currently puts SK Telecom, DXYZ and Zoom ahead of Amazon, Alphabet and Salesforce.
Gold is still a real-rate trade in the short term, but rising U.S. debt and fiscal pressure are changing its medium-term relationship with Treasury yields.

AI server orders, cloud utilization, and HBM contracts all point to real demand. The harder question for 2027 is whether high prices and new qualified supply begin to change the cycle.
AI infrastructure spending is moving beyond GPUs and HBM into substrates, PCB materials, high-end circuit boards and passive components. The key investment question is which parts of the supply chain can retain the most profit.
Why semiconductor stocks fell after strong earnings: CXMT changed the memory supply narrative, while Korea’s leveraged unwind amplified the selloff.

AI demand is still growing, but as GPUs, long-term compute contracts, project finance, and customer credit become more tightly connected, the real risk may be hiding in how the expansion is funded.
CCXI could become a rare public-market window into humanoid robotics, but investors still need to separate theme exposure from proven economics.

Nvidia is showing that the unit cost of AI production is falling. Investors are asking whether cheaper tokens can turn into visible profits and free cash flow fast enough.
Micron’s earnings are not a low-expectation setup. The market already knows HBM demand is strong. The real question is whether Micron’s profits reflect a traditional memory upcycle or a structural AI-driven shift in memory supply.
Anthropic's IPO risk is framed around commercialization control rather than model performance.
Join readers who receive our best ideas and insights straight to their inbox.